
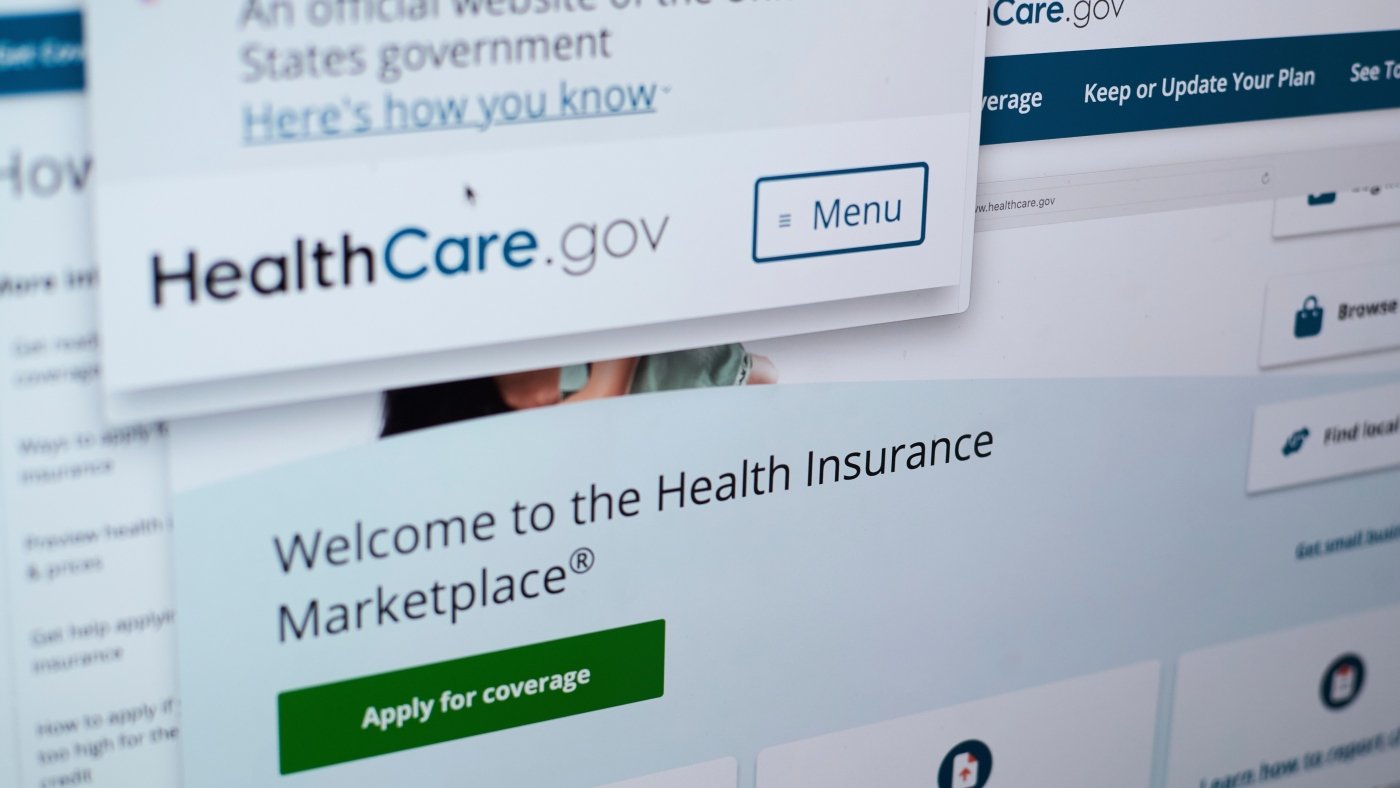

Pages from the U.S. Inexpensive Care Act medical health insurance web site healthcare.gov are seen on a pc display in New York, Aug. 19, 2025. (AP Picture/Patrick Sison, File)
Patrick Sison/AP
conceal caption
toggle caption
Patrick Sison/AP
For the thousands and thousands of Individuals who purchase Inexpensive Care Act insurance coverage, there’s nonetheless time left to enroll for 2026. However premium will increase and the expiration of enhanced tax subsidies have led to larger-than-expected prices.
Involved buyers, questioning if there’s something they will do, are consulting insurance coverage brokers or speaking to representatives at ACA market name facilities.
“We’re listening to from individuals with advanced medical circumstances who do not assume they will survive if they do not have entry to medical care,” stated Audrey Morse Gasteier, government director of the Massachusetts Well being Connector, that state’s insurance coverage market.
And a few are contemplating going outdoors the ACA to seek out extra reasonably priced choices. However that requires warning.
Congress is unlikely to increase the improved subsidies earlier than the yr’s finish. Late Wednesday, the Home handed a package deal of measures favored by conservatives that doesn’t tackle the subsidies and is basically seen as useless on arrival within the Senate. Earlier Wednesday, nevertheless, 4 GOP moderates joined with Democrats to signal a discharge petition to drive a vote — doubtless in January — on a three-year extension. The Senate and President Trump would additionally should approve the measure, but when prolonged the subsidies may be utilized retroactively.
In the meantime, the deadline for selecting a well being plan is shortly approaching. The official finish of open enrollment is ready for Jan. 15 for protection beginning Feb. 1. In most states, it is already too late to enroll for protection beginning Jan. 1.
Listed below are 5 issues within the decision-making course of:
1. Brief-term plans: ‘It’s a must to be wholesome’
Some ACA buyers would possibly discover themselves contemplating short-term insurance policy bought outdoors the government-run marketplaces — or steered towards the plans by insurance coverage brokers. Be cautious.
Brief-term plans are simply that: insurance coverage initially designed as non permanent protection for conditions like altering jobs or attending college. They’ll look rather a lot like conventional protection, with deductibles, copayments, and collaborating networks of hospitals and medical doctors. Nonetheless, they aren’t ACA-compliant plans and usually are not out there on the official ACA marketplaces.
They’re typically cheaper than ACA plans. However they cowl much less. For instance, in contrast to ACA plans, they will impose annual and lifelong caps on advantages. The overwhelming majority don’t cowl maternity care. Some may not cowl prescribed drugs.
Brief-term plans require candidates to finish a medical questionnaire, and insurers can exclude protection or cancel a coverage retroactively for these with preexisting medical circumstances. Additionally, relying on the phrases of the actual plan, an individual who develops a medical situation in the course of the protection interval may not be accepted for renewal.
As well as, short-term plans usually are not required to cowl care on the ACA’s guidelines of important advantages, corresponding to preventive care, hospitalization, or emergency providers.
The shortcomings of the plans, which critics say are typically marketed in deceptive methods, have led Democrats to label them “junk insurance coverage.” The Trump administration argues they’re appropriate for some individuals and has sought to make them extra broadly out there.
“We suggest it when it is sensible,” stated Joshua Brooker, a Pennsylvania insurance coverage dealer. “But when you are going to enroll in short-term protection, it is advisable to know which containers are unchecked.”
“They don’t seem to be for everybody. It’s a must to be wholesome,” stated Ronnell Nolan, the president and CEO of Well being Brokers of America, a commerce group.
And so they’re out there in solely 36 states, based on KFF, a well being info nonprofit that features KFF Well being Information. Some states, corresponding to California, prohibit them. Others set tight restrictions.
2. Watch out for protection that is not complete
There are different forms of well being protection supplied by gross sales brokers or different organizations.
One sort, known as an indemnity plan, is supposed to complement a conventional medical health insurance plan by paying towards deductibles or copayments.
These plans would not have to observe ACA protection guidelines, both. Usually, they pay a set greenback quantity — say a couple of hundred {dollars} a day — towards a hospital keep or a smaller quantity for a health care provider’s workplace go to. Usually these funds fall in need of the total prices and the policyholder pays the remaining. They often additionally require customers to fill out medical kinds stating any preexisting circumstances.
One other kind, a faith-based sharing plan, swimming pools cash from members to cowl their medical payments. The plans usually are not required to maintain any certain amount of monetary reserves and members usually are not assured that the plans pays their well being bills, based on the Commonwealth Fund, a basis that helps well being care analysis and enhancements to the well being system.
Sharing plans expanded past religion communities after the ACA was adopted. Like short-term plans, they value lower than ACA plans but in addition do not should observe ACA guidelines.
They aren’t thought-about insurance coverage, and a few have been accused of fraud by state regulators.
“Sure, it’s cheaper, and sure, it does work for some individuals,” Nolan stated. “However it is advisable to perceive what that plan does. It might be my final resort.”
3. Take into account a ‘Bronze’ or ‘Catastrophic’ plan, however concentrate on deductibles
For these wanting to stick with ACA plans, the bottom premiums are typically within the classes labeled “catastrophic” or “bronze.”
Jessica Altman, government director of California’s ACA alternate, stated her state has observed an uptick in enrollments in bronze-level plans. They’ve decrease premiums however excessive annual deductibles — the quantity a buyer should spend earlier than most protection kicks in. Deductibles for bronze plans common almost $7,500 nationally, based on KFF.
Another choice, new for 2026, is expanded eligibility for catastrophic plans, which was restricted to individuals youthful than age 30. Because the title suggests, they’re supposed for individuals who need medical health insurance simply in case they endure a catastrophic well being situation, corresponding to most cancers or accidents from a automotive accident, and the plans can have deductibles as excessive because the ACA’s annual restrict on out-of-pocket spending — $10,600 for a person or $21,200 for a household.
However now individuals dropping subsidies due to the expiration of the improved tax credit may qualify for the plans. Nonetheless, they will not be out there in each area.
Lauren Jenkins, a dealer in Oklahoma, stated a few of her purchasers incomes lower than $25,000 this yr had certified for very low-cost or free plans with the improved subsidies. Subsequent yr, although, their prices could rise to $100 or extra per thirty days for a “silver”-level plan, a step up from bronze.
So she is displaying them bronze plans to deliver down the month-to-month value. “However they may have a $6,000, $7,000, or $10,000 deductible they now should pay,” Jenkins stated. “For individuals solely making $25,000 a yr, that may be detrimental.”
Each bronze and catastrophic plans are eligible to be linked with well being financial savings accounts, which can be utilized to lower your expenses tax-free for medical bills. They’re extra widespread with higher-income households.
4. One other plan could have decrease premiums
It may possibly pay to buy round. Some individuals might be able to discover a decrease premium by shifting to a distinct plan, even one supplied by the identical insurer. There are additionally completely different ranges of protection, from bronze to “platinum,” the place premiums additionally differ. Brooker stated that in some areas “gold”-level plans are cheaper than silver, although that appears counterintuitive.
Additionally, some individuals who run their very own companies however have just one worker would possibly qualify for a bunch plan reasonably than a person coverage. Generally these might be cheaper.
Not each state permits this, Nolan stated. However, for instance, Nolan stated, she has a consumer whose solely worker is his spouse, so she’s going to see whether or not they can get a bunch plan at decrease charges.
“Which may work out for them,” she stated.
ACA charges for small group plans (fewer than 50 workers) differ regionally and usually are not at all times cheaper than particular person protection, Brooker stated.
“It is fairly everywhere in the board as to the place the charges are higher,” he stated.
5. Different guidelines of the street
Insurance coverage consultants encourage individuals to not wait till the final minute to no less than take preliminary steps. Customers can go onto the official federal or state market web site and fill out or replace an utility with required revenue and different info essential to find out what the 2026 plan yr holds for them.
As an example, even with out congressional intervention, subsidies is not going to go away completely. They are going to be smaller, although, and there’s an higher revenue restrict — a cutoff for households incomes greater than 4 instances the poverty degree, which involves $62,600 for a person and $84,600 for a pair for 2026.
When purchasing, customers ought to be sure they land on an official ACA web site, as a result of there are look-alikes that will not provide ACA-compliant plans. Healthcare.gov is the official federal web site. From there, individuals can discover web sites serving the 20 states, together with the District of Columbia, that run their very own ACA exchanges.
The federal government websites may direct customers to licensed brokers and different counselors who will help with an utility.
And a reminder: Customers additionally must pay their first month’s premium for protection to take impact.
KFF Well being Information is a nationwide newsroom that produces in-depth journalism about well being points and is likely one of the core working applications at KFF.


